

Paper Accepted in Quantitative Finance (the Most Prestigious International Journal in Finance) (First author: Kim Hyuk-soo; Corresponding author: Professor Kim Se-jun)
Files

The paper 'Reduction of estimation error impact in the risk parity strategies', written by Kim Hyuk-soo of the Department of Computer Science & Engineering (combined master's–doctoral, 9th semester; supervisor: Professor Kim Se-jun) and Professor Kim Se-jun, was published in Quantitative Finance in August 2021.
The paper addresses problems that can arise when estimation error is present in the process of implementing a risk parity portfolio.
Risk parity is one of the asset management strategies hedge funds use to diversify risk. The paper shows that when the risk parity strategy is applied to multi-factor portfolios, which have drawn much attention recently, errors present in covariance estimates prevent proper
risk diversification, and proposes an algorithm that mitigates this problem.
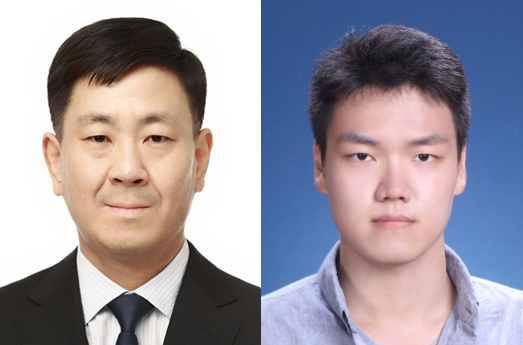
▲ From left: Professor Kim Se-jun (supervisor), Department of Computer Science & Engineering; Kim Hyuk-soo (combined master's–doctoral student)
*This research was carried out with the support of the National Research Foundation of Korea.