

Paper Accepted by Mathematics (a Distinguished International Journal, 95.8th Percentile in Mathematics by 2023 JCR) (First author: Kim Hyuk-su; corresponding author: Professor Kim Se-jun)
Files

Paper Accepted by Mathematics (a Distinguished International Journal, 95.8th Percentile in Mathematics by 2023 JCR) (First author: Kim Hyuk-su; corresponding author: Professor Kim Se-jun)
A paper written by Kim Hyuk-su of the Department of Computer Science & Engineering (doctorate awarded February 2024; supervisor: Professor Kim Se-jun) and Professor Kim Se-jun,
'Estimating Asset Pricing Models in the Presence of Cross-Sectionally Correlated Pricing Errors', has been published in Mathematics.
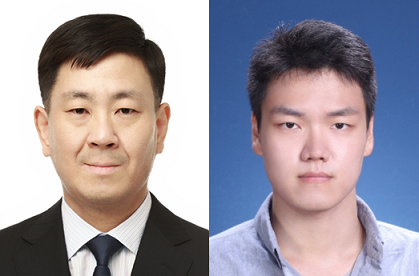
▶ (From left) Professor Kim Se-jun (supervisor), Kim Hyuk-su (doctoral graduate)
The paper presents a new estimation method for asset pricing models that captures phenomena present in financial data which existing estimation methods did not take into account. The research proposes a min-max optimization problem that simultaneously minimizes the time-series co-movement and the cross-sectional pricing errors of the returns of many financial assets, and estimates factors and factor loadings from it. It also presents an approximation algorithm for solving this optimization problem. Empirical analysis demonstrates that the proposed estimation method outperforms existing factor models when the explanatory power of the asset pricing model is limited.