

Regular Paper Accepted at the Outstanding International Conference IEEE BigData 2022, with a Student Travel Award
Files

Regular Paper Accepted at the Outstanding International Conference IEEE BigData 2022, with a Student Travel Award
The paper 'Exploring Multi-Time Context Vector and Randomness for Stock Movement Prediction', written by Seo Kang-hyun (combined master's–doctoral student and first author) of the Machine Learning Laboratory in the Department of Computer Science & Engineering and corresponding author Professor Yang Ji-hoon (supervisor), has been accepted as a regular paper at the 2022 IEEE International Conference on Big Data (IEEE BigData 2022). First author Seo Kang-hyun will also receive a Student Travel Award at the conference.
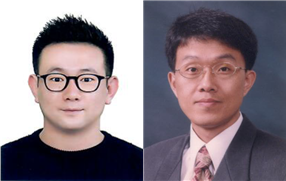
▲ (From left) Seo Kang-hyun (combined master's–doctoral student) and Professor Yang Ji-hoon (supervisor)
IEEE BigData is an international conference for presenting and sharing the latest theory and diverse applied research using big data in computer science, and is listed among the KIISE outstanding software conferences. The Student Travel Award that Seo Kang-hyun will receive is given to students who have written papers of outstanding quality among those accepted, and covers a portion of the attendance costs.
The research predicts, as a binary classification problem, whether the next day's closing stock price will rise or fall relative to the previous day, applying recurrent neural networks — which perform strongly on time-series data — together with the multi-head attention technique widely used in natural language processing and computer vision.
The motivation for the research came from the observation that when people actually decide on stock investments they predict the next day's price movement by looking at candlestick charts over various lengths to gather relevant information; the two deep learning models above were combined accordingly. In addition, to reflect price movements caused by 'noise traders' — a concept from market microstructure theory in economics, referring to investors who trade impulsively on subjective judgement or unfounded rumour rather than on rational analysis grounded in accurate information — a trainable Gaussian noise distribution was set up and noise sampled from it was used in the price prediction.
In the experiments, the stock price prediction results showed improved prediction accuracy and reliability over the then state-of-the-art models, and a stock-based portfolio trading simulation using backtesting also showed high cumulative returns.
IEEE BigData 2022 link: https://bigdataieee.org/BigData2022/